

Airtel: Recharge, Bank & Loans
by Airtel
4.0
- Safety
- 100% Safe
- Category
- Finance
- Ratings
- 4.0
- Price
- Free
- Download
- 500.00M
This app is secure, reliable, free to install, and offers fast downloads without any risks or malware.
Screenshots
 Analysis by Getfullapps
I use finance apps differently from entertainment apps: I want speed, but I also want to understand what I am approving before money moves. Airtel: Recharge, Bank & Loans sits in that practical space, combining mobile recharges, bill payments, UPI and other financial services in one place. After spending time with it, I see the appeal clearly: it can reduce the number of separate apps needed for routine payments. At the same time, its broad scope means you need to pay attention to screens, permissions and confirmation steps rather than treating it like a simple recharge shortcut.
The app is free, made by Airtel, and available for Everyone. It has been around since Jul 7, 2016, and its reach is substantial, with over 500 million installs and a 4.0 average from around 7.9 million ratings. Those figures tell me that it is not a niche wallet used by a small group of enthusiasts. It is a familiar tool for many people, especially Airtel customers, although the usefulness of its wider payment functions matters more than the mobile network connection alone.
What I found when using Airtel for everyday money tasks
I found that Airtel works best when I treat it as a repeatable home for familiar tasks rather than a place to explore every financial offer. I’ll look at how a simple routine can make recharges, bills and UPI easier to manage, then turn to the settings and safeguards worth checking before making that routine a habit.
A broad finance hub rather than just a recharge screen
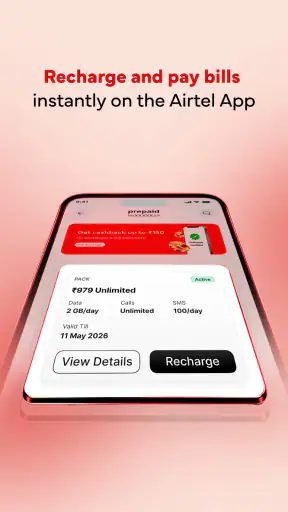
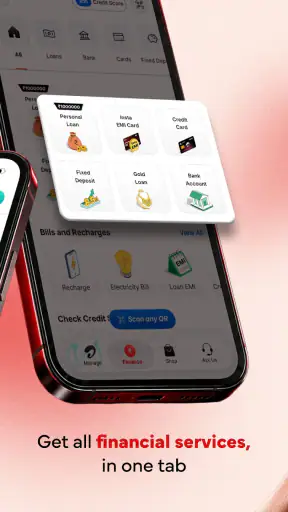
The first thing to understand is the app’s shape. A traditional operator app might focus mainly on prepaid top-ups, data packs and account information. This one reaches further into finance, with UPI, bills, rewards and banking-related services presented alongside recharge tools. That makes it convenient when several small tasks arrive together: renewing a phone plan, paying an electricity bill and sending money can happen from the same general environment.
That convenience is also the main reason I would not describe it as a minimalist app. There are more destinations to explore, more offers or service prompts to interpret, and more opportunities to pause before confirming something. If all I wanted was a quick mobile recharge, a simpler operator-focused screen could feel easier. If I regularly manage several household payments, the wider layout becomes much more useful.
One realistic example is a busy evening before a trip. I can check the mobile balance, recharge the number that needs data, pay a pending bill and use UPI for a small transfer without switching between a carrier app, a separate payment app and a bill portal. The time saved is not dramatic for one transaction, but it becomes noticeable when these jobs repeat every month.
Why Airtel customers may get the smoothest experience
Airtel’s involvement gives the app an obvious home advantage for people already using Airtel services. The connection between a mobile account and recharge activity feels more natural than it would in a general-purpose payment app. I can see why someone who already receives Airtel-related prompts would prefer keeping those tasks close to the rest of their financial activity.
Articles to Explore Next

Uber Eats Makes Dinner Easier to Manage, but the Fees Add Up

Google Photos Turns a Camera Roll Into a Library You Can Find Your Way Through

Canva on Mobile: Adopt It for Quick Visuals, Test It for Demanding Work

Google Drive Keeps Work Moving Until It Doesn’t

Switching to Weather - By Xiaomi Means Relearning Your Forecast Routine

Ludo King and the Social Life of a Lucky Six
However, I would not choose it solely because I use Airtel. The relevant question is whether the payment, bill and UPI tools fit my habits. A person who already has a trusted banking app and a separate bill manager may gain little by adding another financial dashboard. The app makes more sense when consolidation is genuinely useful, not simply because one company offers many services under one roof.
Trust begins with the moment before payment
Finance apps earn trust through small details. Before tapping a final confirmation button, I want the recipient, amount, payment method and any visible charge to be understandable. I also want enough separation between browsing a reward or loan-related service and actually applying, paying or authorizing something. With a broad app such as this, I recommend slowing down at those transitions.
My practical rule is simple: treat every payment screen as a fresh decision. Do not assume that a previous choice, saved account or displayed offer is still the option you intend to use. Recheck the destination and amount, especially when moving between recharge, bill payment and UPI. This is not a criticism unique to Airtel; it is the sensible habit for any app that can move money.
Controls I would check before regular use
The most important controls are the ones that determine who can access the account and how a transaction is authorized. I would begin by reviewing the sign-in method, device security and any available payment authentication settings. A phone lock, a protected SIM and a private UPI PIN are basic safeguards, but they matter more than a colorful rewards section.
I would also inspect notification settings. Payment alerts are useful because they help me spot activity quickly, but promotional messages can make a finance app feel noisier than necessary. Separating essential transaction notices from marketing-style prompts, where the app allows it, improves both privacy and attention. Missing a genuine payment alert because it is buried among offers is an avoidable problem.
Another useful habit is to remove old or unused accounts from my own routine. If I have changed a biller, phone number or bank relationship, I do not want outdated choices sitting near the active ones. Even when an app remembers details for convenience, I prefer checking them periodically and keeping only what I still recognize. That reduces the chance of selecting the wrong destination under time pressure.
Permissions and data-sensitive moments
I pay closer attention to permissions in a finance app than I do in a casual game because the context is more sensitive. The right approach is not to approve everything automatically or to reject every request without reading. I look at what the app is asking for, when it asks, and whether the request makes sense for the task I am trying to complete.
For example, a permission request appearing while I am only browsing recharge options deserves a pause. A request shown during a specific payment or verification step may have a clearer purpose, but I still want to know what I am authorizing. If a feature works without a permission, I prefer leaving that access disabled. If refusing it prevents a service from working, I decide whether that service is important enough to justify the trade-off.
Data-sensitive moments are not limited to permissions. They include entering a mobile number, selecting a bank account, scanning or sharing a payment code, opening a loan-related section and responding to identity or account prompts. I avoid doing these tasks on an unfamiliar device or an unsecured public network. I also check the recipient carefully before entering a PIN, because a successful authentication does not correct a wrong destination.
I would not make claims about Airtel’s data practices beyond what is visibly presented in the app and its own notices. My recommendation is to read the privacy and consent screens when they appear, especially after an update or when opening a new financial service. Look for clear explanations of what is being requested and which choices are optional. If a screen feels rushed or ambiguous, I postpone the action rather than accepting it just to reach the next page.
UPI is convenient, but convenience needs discipline
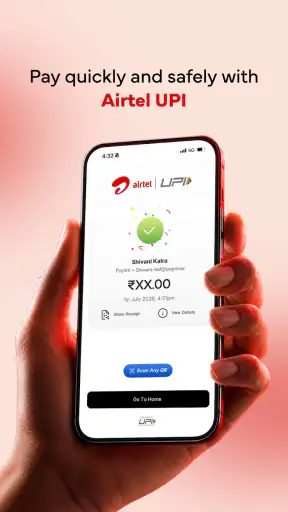
UPI makes everyday transfers fast, and having it near recharges and bills is one of the app’s strongest practical ideas. I can imagine using it for splitting a meal, paying a local merchant or sending money to someone I know. The downside is that speed can encourage careless confirmation. The familiar flow may feel routine even when the amount or recipient deserves a second look.
I recommend separating three checks: who will receive the money, how much will be sent, and whether the action is a payment request or a transfer. A request to enter a UPI PIN should be treated as approval to send money, not as a step required to receive it. That distinction is especially important for less experienced users and for anyone helping a family member set up digital payments.
When a transaction appears delayed, I would avoid repeating it immediately. First I would check the transaction history, bank messages and recipient status. Duplicate payments are more frustrating to resolve than a short wait. Keeping screenshots or reference details for an unusual failure can also make support conversations clearer, although I would store them privately and avoid sharing sensitive information in public channels.
Bill payments and recurring household routines
Bill payment is where the app can become genuinely useful for a household. Instead of remembering several provider portals, I can organize recurring obligations around one payment routine. The hidden advantage is not merely fewer taps; it is the possibility of creating a consistent monthly checkpoint. I can review which bills are due, confirm each account and then keep a personal record of what was paid.
Still, I would not rely on memory inside the app alone. I keep the biller name and account identifier in my own secure notes, because a saved selection can become confusing when several family accounts look similar. Before paying, I compare the displayed customer details with the bill or previous record. This extra check is worthwhile when one mistake could affect another person’s service.
Rewards may make a routine payment feel more attractive, but I treat them as secondary. I never increase spending or choose an unfamiliar service simply to chase a reward. The sensible comparison is the final value and the reliability of the payment, not the most eye-catching promotional message. For me, a reward is a bonus only after the bill is correct and the terms are understandable.
Banking and loan-related areas require a slower pace
The banking and loans wording makes the app broader than a standard recharge utility. That can be helpful for users who want to explore financial services without installing another application, but it also raises the stakes. A recharge is usually a small, familiar purchase; a loan-related decision can affect future repayments, personal information and long-term finances.
I would approach those sections as information and application areas, not as instant solutions for a cash shortage. Before proceeding, I would read the repayment details, eligibility language, fees, schedule and consequences of late payment wherever they are shown. I would not assume that a prominent offer is automatically the cheapest or most suitable option. Comparing it with my bank and other regulated alternatives is essential.
This is one of the clearest situations where another option may be better. If I already have a direct relationship with a bank and understand its loan terms, its official app or branch may provide a clearer comparison and a more established support path for that specific borrowing decision. Airtel can be a convenient place to investigate, but convenience should never replace affordability checks.
How much control does the user really have?
User agency comes from being able to choose deliberately, not from having every possible feature in one screen. I appreciate the ability to decide which payment method to use, whether to open a particular service and whether a permission is necessary. I also want the freedom to leave a promotional path without feeling that I must complete it to use an unrelated function.
In practice, I would create a personal boundary around the app. I use it for known tasks, ignore unsolicited financial messages and open new offers only when I have time to evaluate them. I do not share one-time passwords, UPI PINs or full account details with anyone claiming to provide support. If a message creates urgency, I verify it through an official route rather than using a number or link supplied in that message.
Families should agree on who is allowed to use a shared phone and which accounts are connected. A child-friendly age label does not mean every financial feature is appropriate for every child. Adults should supervise payment setup and explain that a PIN authorizes a transaction. For older relatives, the best setup may be a limited routine with familiar billers rather than unrestricted exploration of every section.
Performance, updates and daily friction
The current version is 4.149.2 and supports Android 7.0 or later. That makes compatibility reasonably broad for people who keep older Android phones, although actual smoothness will still depend on the device, storage, connection and the number of services being loaded. I would keep the app updated through the official store because finance tools benefit from current security and compatibility fixes.
My main usability concern is not that the app lacks options, but that options can compete for attention. A person arriving to pay one bill may encounter recharges, rewards, banking prompts and other financial routes. Clear labels help, yet I still prefer using search or a known shortcut when available instead of browsing every promotional card. The more focused my task, the less likely I am to make a selection by accident.
Support is another area where expectations should stay realistic. Payment problems often involve more than one party: the app, a bank, a biller or a network. I would first identify which side shows the failed or pending status, then keep the transaction reference and contact the appropriate support channel. Repeating the same payment without checking can turn a technical issue into a duplicate charge.
Who should use it, and who should skip it?
I think Airtel is a good fit for Airtel customers who want recharge and bill tasks close to UPI, or for households trying to reduce the number of finance apps they use. It is also reasonable for someone who values a single starting point and is comfortable reviewing each service before using it. The app’s large user base and long presence make it familiar, but familiarity should support careful use rather than replace it.
I would skip it if I only need the simplest possible recharge flow and find a multi-service dashboard distracting. I would also avoid making it my main financial environment if I prefer a dedicated bank app for account management, a specialist UPI app for transfers or a separate bill organizer with fewer commercial prompts. People who dislike reading consent screens or checking recipients before payment may be better served by a narrower routine they understand completely.
For privacy-conscious users, the decision should come from inspecting the app’s visible permissions, notices and account choices on their own device. I would not install a finance app merely because it offers rewards, and I would not reject this one based on assumptions about data handling that are not shown. The right test is whether the controls are understandable enough for me to make informed choices and whether I am willing to maintain those choices over time.
My cautious verdict after using it
Airtel: Recharge, Bank & Loans is strongest when convenience is paired with attention. It brings mobile recharges, bills and UPI into a familiar Airtel environment, and the free price makes it easy to try. The 4.0 average from millions of ratings suggests broad acceptance, while the app’s scale also means experiences can vary with device, bank, biller and connection.
I would recommend it to a friend who wants one practical place for recurring payments and understands that financial convenience comes with responsibility. My advice would be to configure only the services you need, review permissions when they appear, separate transaction alerts from promotional noise where possible, and verify every recipient before entering a PIN. I would keep loan-related decisions outside the impulse of a quick tap and compare them carefully with direct alternatives.
In the end, I see this as a useful finance companion rather than an app that should replace every financial relationship. It can simplify ordinary routines, but it cannot decide whether a payment is wise, whether a loan is affordable or whether a permission is acceptable for you. Used with those limits in mind, it is a capable choice for people who want Airtel services and everyday digital payments together without pretending that one dashboard removes the need for judgement.
Pros
- Quick mobile recharges with support for multiple payment methods.
- Airtel Thanks rewards can provide discounts and partner benefits.
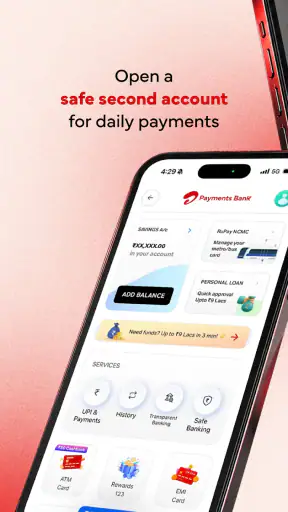
- Airtel Payments Bank enables convenient bill payments and money transfers.
- Loan and financial services are accessible directly within the app.
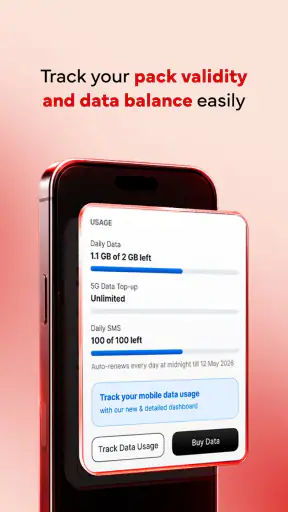
- Useful account tools for checking data, balance, and plan validity.
Cons
- Some financial features may require extra verification or eligibility checks.
- Loan availability and terms can vary by user, location, and credit profile.
- The app may promote Airtel offers through frequent notifications.
- Certain services may depend on Airtel network coverage or regional support.
- Performance can feel slower on older phones or weaker internet connections.
FAQs for Airtel: Recharge, Bank & Loans
What is Airtel: Recharge, Bank & Loans used for?
Airtel: Recharge, Bank & Loans is a multifunctional app designed for Airtel customers who want to manage mobile services and selected financial products in one place. After installing it, users can typically recharge prepaid numbers, pay utility bills, check account details, access Airtel Money or banking features where available, and explore loan-related services. The exact options depend on your country, account type, and Airtel’s current service availability.
Can I recharge any mobile number and pay bills through the Airtel app?
The app generally supports Airtel prepaid recharges and may also allow payments for other mobile networks, depending on the market. It can include bill payments for services such as electricity, television, internet, or water, although available categories vary by region. Before confirming a transaction, carefully check the phone number, selected plan, amount, and payment method because completed recharges or bill payments may not always be reversible.
Are Airtel Bank and loan services available to every user?
No. Airtel’s banking, wallet, savings, credit, and loan features are usually subject to location, eligibility requirements, identity verification, and local regulations. You may need an active Airtel account, a verified phone number, valid identification, and an acceptable credit or transaction history. Loan availability, limits, interest rates, repayment periods, and fees should be reviewed inside the app before accepting any offer, since they can differ between users.
Is Airtel: Recharge, Bank & Loans safe to use?
The application is intended to provide official Airtel services, but users should still take normal security precautions. Download it only from a trusted app store, confirm that the developer is Airtel or the authorized provider, and keep the app updated. Never share your password, PIN, one-time password, or banking verification code with anyone. Use a secure connection, enable device protection, and contact official Airtel support if you notice an unfamiliar transaction.
What should I do if a recharge fails or money is deducted without the service being completed?
First, open the transaction history and check whether the payment is marked as pending, successful, or failed. Avoid repeating the transaction immediately, as the original request may still be processing. Save the reference number, amount, date, and screenshots, then contact Airtel customer support through the official in-app help section or verified support channels. Refund timing can depend on the payment provider, bank, or biller, so keep the confirmation details until the issue is resolved.

Airtel: Recharge, Bank & Loans
This site provides independent information about third-party apps and is not affiliated with, or the owner, developer, or distributor of, any app featured here. App names, logos, and trademarks belong to their respective owners. Developer details are provided for reference; please contact the developer directly via Socialcare@airtel.com, visit https://www.airtel.in/, or review their http://www.airtel.in/forme/privacy-policy/.










